

Saving for retirement is one of the primary goals of financial planning … and individual retirement accounts (IRAs) are one of the most important vehicles for achieving your retirement saving goals.
However, you can only put so much in IRAs each year. The U.S. tax laws include IRA contribution limits that restrict how much you can squirrel away in IRAs during the year. The amount you can put in a Roth IRA each year can also be reduced (potentially to zero) if your income is above a certain amount.
Good news, though: The IRA contribution limits and Roth IRA income limits are adjusted most years to account for inflation.
Let me show you the new IRA contribution limits and Roth IRA income limits below to get an idea of how much you’ll be able to save for retirement with your IRAs for the rest of this year and in 2027.
Related: 401(k) Contribution Limits for 2027
Featured Financial Products
Traditional IRAs vs. Roth IRAs
Before getting into the IRA contribution limits and Roth IRA income limits for 2025 and 2026, it’s probably best to explain the differences between traditional IRAs and Roth IRAs. The key difference is how—or should I say, when—they are taxed.
With a traditional IRA, your contributions are made with “pre-tax” dollars. That generally means contributions are tax-deductible in the year you make them (although your tax-deductible contributions might be limited if you or your spouse is covered by a workplace retirement plan or your income is too high). Money in the account then grows on a tax-deferred basis, and is subject to federal income tax when you make withdrawals in retirement.
On the other hand, contributions to a Roth IRA are made with “after-tax” dollars. In other words, they’re not tax-deductible. However, funds in the account grow tax free, so you won’t pay taxes on withdrawals in retirement.
In addition, you might also qualify for a tax credit of up to $1,000 ($2,000 for married couples filing a joint tax return) for putting money into either a traditional or Roth IRA. However, this credit—commonly called the Saver’s Credit—is only available to low- and moderate-income individuals. So, to claim the credit, your federal adjusted gross income (AGI) must be at or below a certain amount, which is based on your filing status.
Related: IRA vs. 401(k): How These Retirement Accounts Differ
Early Withdrawal Penalties
A 10% early withdrawal penalty might apply if you take money out of an IRA too soon.
With a traditional IRA, you might be hit with the penalty if you withdraw money from the account before you’re 59½ years old. The penalty is in addition to any income tax imposed on the amount withdrawn.
The penalty is less likely to apply when you take money out of a Roth IRA. Any contributions you make to a Roth can be withdrawn tax free and penalty free at any time. However, if you withdraw investment gains before age 59½, you might have to pay taxes and the 10% early withdrawal penalty.
There are exceptions to the 10% early withdrawal penalty, though. Penalty-free withdrawals from either a traditional or Roth IRA are possible if the money is used to pay certain education expenses. A one-time early withdrawal of up to $10,000 is also permitted if the money is used for a first-time home purchase. Other exceptions might also apply.
Finally, you’re also required to take out a certain amount of money from a traditional IRA each year when you turn 73 years old. These mandatory withdrawals are called required minimum distributions. They aren’t necessary with Roth IRAs, though.
Related: 10 Best Investments for Roth IRA Accounts
IRA Contribution Limits for 2026 + 2027
Since we still have time left in 2026 to make IRA contributions, let’s start with the current IRA contribution limits.
IRA Contribution Limits for the 2026 Tax Year
For the 2026 tax year, the annual contribution limit for a traditional or Roth IRA is $7,500 for people under age 50. That’s up from $7,000 in 2025.
If you’re 50 or older, you can contribute an additional $1,100 for the 2026 tax year (up $100 from 2025), called a “catch-up” contribution. That means you can kick in a total of $8,600 for 2026 ($600 better than 2025).
The annual limits are combined limits that apply to all your traditional and Roth IRAs. So, for example, if you’re under age 50 and put $5,000 in a traditional IRA in 2026, then you can’t put more than $3,100 in a Roth IRA (or any other IRA) for the 2026 tax year.
YATI Tip: You have until the tax filing deadline for the year to make contributions to an IRA. So, for example, you have until April 15, 2027, to put money in an IRA for the 2026 tax year. If you request an automatic filing extension for your 2026 tax return, you’ll have until Oct. 15, 2027, to contribute to an IRA for the 2026 tax year. Similar deadlines will apply for 2027 IRA contributions.
Related: 10 Best Rollover IRA Accounts [Where to Roll Over a 401(k)]
IRA Contribution Limits for the 2027 Tax Year
We didn’t get any changes for the coming tax year. The 2027 annual contribution limit for traditional and Roth IRAs will remain $7,500 for people under age 50. Catch-up contributions are the same, too, at $1,1000 for those age 50 or older, for a combined total of $8,600.
Roth IRA Income Limits
The amount you can contribute to a Roth IRA might be less than the year’s IRA contribution limit (and possibly $0) if your income is above a certain amount. That’s because Roth IRAs also have income limits that you need to worry about if you’re a high-earner.
Roth IRA Income Limits for the 2026 Tax Year
For the 2026 tax year, the maximum amount you can contribute to a Roth IRA is gradually reduced to zero if your 2026 modified AGI is:
- At least $153,000 but less than $168,000 for single and head-of-household filers ($150,000 to $165,000 for 2025)
- At least $242,000 but less than $252,000 for joint filers ($236,000 to $246,000 for 2025)
That also means you can’t contribute to a Roth IRA at all for 2026 if your modified AGI for the year is:
- $168,000 or more if you use the single or head of household filing status on your tax return ($165,000 for 2025)
- $252,000 or more if you’re married and file a joint return ($246,000 for 2025)
If you’re married but file a separate tax return, your annual maximum contribution is gradually reduced to zero if your modified AGI is between $0 and $10,000.
Roth IRA Income Limits for the 2027 Tax Year
As with the basic IRA contribution limits, the Roth IRA income limits are adjusted for inflation each year. The IRS released the new income limits for 2027 when it announced the general IRA contribution limits:
For the 2027 tax year, the maximum amount you can contribute to a Roth IRA is gradually reduced to zero if your 2027 modified AGI is:
- At least $158,000 but less than $173,000 for single and head-of-household filers ($153,000 to $168,000 for 2026)
- At least $250,000 but less than $260,000 for joint filers ($242,000 to $252,000 for 2026)
That also means you can’t contribute to a Roth IRA at all for 2027 if your modified AGI for the year is:
- $173,000 or more if you use the single or head of household filing status on your tax return ($168,000 for 2026)
- $260,000 or more if you’re married and file a joint return ($252,000 for 2026)
If you’re married but file a separate tax return, your annual maximum contribution is gradually reduced to zero if your modified AGI is between $0 and $10,000.
Related: Roth IRA vs. 529 Plan: Which Is Better For College Savings?
Where to Open an IRA
If you currently don’t have a traditional IRA or Roth IRA, perhaps now is the time to open one. Even if you have a 401(k) account through your employer, you can still contribute to an IRA—and save even more for retirement.
Here’s a look at our top-rated platform for people starting up an IRA:
Plynk (Best Investment App for Beginners)
- Available: Sign up here
- Best for: Beginner investors
- Platforms: Web, mobile app (Apple iOS, Android)
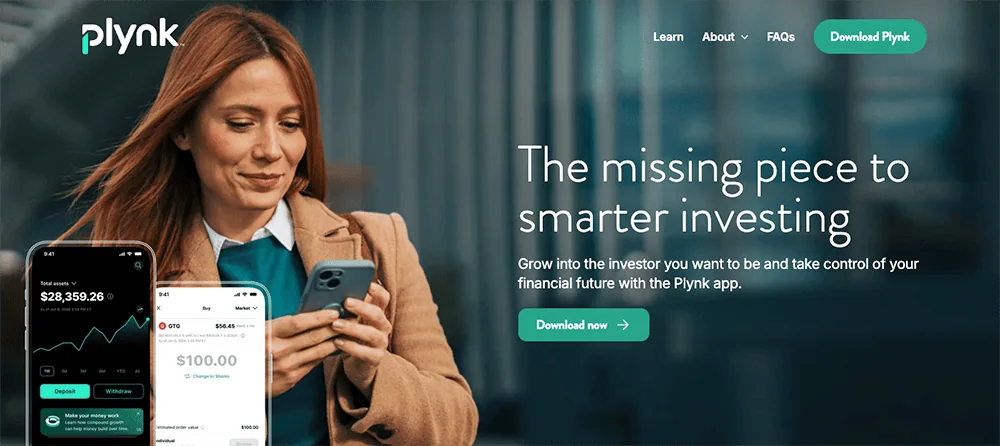
Plynk® is an investing app designed to not only help you start putting your money to work, but teach you about the markets and your money along the way—and now it will help you grow your dividend income.
The Plynk app charges no account opening fees and lets you start investing with as little as $1. It offers commission-free trades on 5,000 stocks and nearly 2,000 ETFs, and also provides access to more than 50 mutual funds and four cryptocurrencies. You can use the app as a traditional brokerage account, but if you’d prefer the potential tax advantages of retirement accounts, the Plynk app also allows you to open traditional IRAs and Roth IRAs.
One of the app’s newest features is a dividend match. Plynk will provide a cash match of 25% on dividends generated within the account, allowing you to earn up to $250 extra annually.
Begin today: Sign up with Plynk using our exclusive link to kick-start your investing journey.
- Plynk® is an effective yet beginner-friendly way to start investing in thousands of stocks, ETFs, mutual funds, and cryptocurrencies.
- Plynk charges no account opening fees, and you can start investing for as little as $1.
- Enjoy commission-free trades* on 5,000 stocks and more than 3,400 ETFs. Plynk also supports mutual funds and cryptocurrencies.
- Boost your yield with a cash match of 25% on dividend income.**
- Earn a 3.55% APY on uninvested cash.
- Track dividends and interest with Income Hub.
- Put your investing on autopilot with automated investing or Steady Start.
- Just getting started? Simulated trading and virtual portfolios help you get your feet wet and build experience without putting any money at risk.
- No account fees
- Smart design and smooth user experience
- Fractional shares
- Designed for beginning investors
- Virtual portfolios and simulated trading
- Earn interest on uninvested cash
- One of the best automated investing programs we've seen (Steady Start)
- Elite educational resources and tools
- Lacks features such as options trading and advanced charting that more experienced traders prefer
SoFi Invest IRAs
- Account minimum: None
- Minimum initial deposit: None
- Fees: No annual or opening fees; $20 closing fee
SoFi offers many perks to its customers, including no annual or opening fees on many different account types. Its SoFi Invest traditional IRA or Roth IRA could be a good choice if you’re an existing SoFi customer.
SoFi offers two options catering to different investment styles. Its active investing option lets you choose and manage your own investments. And with its automated investing option, SoFi will select and manage investments on your behalf.
You won’t pay management fees with either account option, and SoFi doesn’t charge commissions for stock or ETF trading. Several other investment choices are also available, including options and margin trading. However, underlying fund fees may apply depending on the investments you choose, and you will have to pay a modest $20 fee to close your account.
As a platform: SoFi’s interface is still very much geared toward younger, less experienced investors—everything is focused on simplicity and ease of use, rather than an expanse of sophisticated tools. SoFi also offers budget-friendly features such as fractional shares, which allow you to invest for as little as $5.
Sign up through the box below.
Related:
- How Much to Save for Retirement by Age Group
- Can I Retire at 60 with $500K? [YES! See Examples of How]
Disclosures
Plynk
All Plynk disclosures can be viewed here.