
No matter what you might think about Congress at any given moment, you have to tip your cap to their creation of the real estate investment trust (REIT).
The establishment of this real estate business structure helped to democratize real estate investing—while most people are priced out of the six-digit figures needed to buy investment homes or the seven- and eight-digit dollar amounts necessary to own commercial properties, REITs allow us to enjoy the gains (and income!) of all sorts of real estate for the uber-affordable cost of a share of stock.
The advent of REITs didn’t take all the bricks off our shoulders, of course. The market can still throw curveballs at REITs, such as the potential for the Federal Reserve to raise interest rates by the end of 2026, which would increase these companies’ borrowing costs and make their dividends a little less attractive compared to the relative safety of bonds. Thus, we still have to research the best REITs to buy if we want to maximize our real estate investments.
But we’ll see if we can help out on that front. Today, I’ll review seven REITs that enjoy high ratings from Wall Street’s research community, including two new picks that have just joined the list as of this update. And true to REITs’ income-friendly nature, this list’s picks range in yield from 2x to 11x what the S&P 500 pays today.
Editor’s Note: Tabular information presented in this article is up-to-date as of Sept. 8, 2026.
Disclaimer: This article does not constitute individualized investment advice. Individual securities, funds, and/or other investments appear for your consideration and not as personalized investment recommendations. Act at your own discretion.
What Are Real Estate Investment Trusts (REITs)?
A real estate investment trust, often referred to as a REIT (pronounced “reet”), is a unique class of investment made up of companies that own (and sometimes operate) real estate-related assets.
Breaking down the name “real estate investment trust” is a good way of helping people understand how this business works:
The first two words (“real estate”) describe the business focus. REITs must derive at least 75% of their gross income from real estate-related income, and 75% of their assets must be real estate-related assets. And if you wonder why I keep saying “related,” that’s because REITs don’t always have to own physical properties—they can own real-estate related assets such as mortgages, too.
The last two words, “investment trust,” are important to understanding REIT ownership. There are certain thresholds that set REITs apart from conventional publicly traded company stocks. For instance, they must have at least 100 shareholders, and they can have no more than 50% ownership resting in the hands of five or fewer investors.
But perhaps the most important rule you need to know about real estate investment trusts is that they must pay at least 90% of taxable income to shareholders in the form of dividends each year. This mandate for income explains’ REITs typically above-average dividend yields. And those yields are one of the biggest selling points to investors.
2 Types of REITs to Know
The REIT universe is sometimes divided into two distinct flavors: equity REITs and mortgage REITs.
While they both deal in real estate, they’re two vastly different businesses and pretty dissimilar investments that can sometimes have very disparate reactions to the same outside forces.
In other words: Investors should know the difference between the two.
Equity REITs
“Equity” is shorthand for a few things, among them “ownership,” typically in a financial asset or company. You’ll frequently hear “equities” used as another term for “stocks,” as a company’s stock represents an ownership stake in that business.
Equity REITs, then, are directly invested in real estate assets. They own or manage properties ranging from office buildings to shopping centers to apartment complexes, leasing that space and generating income from the rents. And publicly traded equity REITs allow you to enjoy that exposure through their shares, which you can purchase through any traditional brokerage account.
Mortgage REITs
Mortgage REITs (or mREITs), on the other hand, don’t traffic in real estate properties—instead, they deal with debt.
Mortgage REITs finance real estate, operating less like a traditional REIT and more like a financial firm. This is done by either originating mortgages, or buying and selling those mortgages and related mortgage-backed securities. The business also commonly involves borrowing heavily to then trade all that mortgage paper at scale. An mREIT’s profits, then, tend to revolve around net interest income (NII): the difference between the interest revenue they generate and the financing costs on all their assets.
This fundamentally makes mortgage REITs riskier than equity REITs. After all, the 2008 financial crisis was caused in large part by financial firms borrowing heavily to invest in the debts of third parties. Particularly in the current interest rate environment, where borrowing is getting steadily more expensive all around, that’s a tough spot to be in.
That said, many mREITs offer twice or even thrice the income potential of equity REITs. These dividends might be at risk of evaporating if things go south, but if they hold up, investors will be richly rewarded for looking beyond the conventional players on Wall Street.
Do you want to get serious about saving and planning for retirement? Sign up for Retire With Riley, Young and the Invested’s free retirement planning newsletter.
The Best REITs to Invest In
You already might be wondering how to decide between mortgage REITs or equity REITs, or whether you should invest in a small commercial real estate firm or a big industrial park operator. After all, there’s a great big world of real estate investing out there!
The answer is: There is no one right answer for everyone. With so many things on Wall Street, your unique risk tolerance and retirement planning needs are critical to deciding the best REITs to buy right now.
The following list should get you pointed in the right direction, however. All seven of these leading real estate investment trusts offer significant income and the potential for long-term upside if things pan out in 2026 and beyond.
All REITs listed in order of yield, from lowest to highest.
Best REIT #7: Equinix
- REIT industry: Datacenters
- Market capitalization: $103.0 billion
- Dividend yield: 2.0%
Equinix (EQIX) is a play on numerous technological megatrends, including cloud computing, big data, and artificial intelligence.
EQIX is the largest global data center and colocation provider for enterprise networks. In other words, Equinix is responsible for the actual server rooms that house all the bits and bytes that power all the content and software we offload to “the cloud” without really considering where the cloud is.
Considering the fact that cloud-based software is now just the normal way of doing business, that creates a massive opportunity for Equinix as one of the largest specialized firms in the space. This digital infrastructure provider boasts almost half a million connections to more than 10,500 customers, with a global reach of 77 metro areas in 36 countries. Those numbers will surely grow, with the company currently working on 46 projects in 32 markets across 22 countries.
“Equinix [second-quarter] results and guidance revisions reflect strengthening demand for its platform that is showing up in stronger bookings, significantly faster RPO growth for its recurring retail revenues, and underlying margin improvement,” Citi analyst Michael Rollins says. “EQIX is continuing to see some early benefits from rising demand for AI inference and agentic workloads.”
Rollins is one of 26 analysts with a Buy-equivalent rating on the stock, which compares well to just six Holds and no Sells. Also ringing in after earnings was BNP Paribas Equity Research senior analyst Nate Crossett, who rates the stock at Outperform (equivalent of Buy).
“We would describe the quarter as generally sound with a modest increase in guidance,” he wrote in late July. “KPIs were generally sound with solid gross bookings (near record levels), and healthy pricing increases; churn was also notably low again. Commentary on the conference call as it relates to bookings was positive (backlog is highest in history). We remain supportive of shares as the commentary remains robust as it relates to overall demand.”
And despite what a relatively modest 2% yield might imply, Equinix has been downright aggressive in sharing its wealth with EQIX holders. The payout has roughly tripled over the past 10 years … it’s just that the shares have risen every bit as rapidly. Equinix’s stock is up 175% on a pure price basis in the past decade. Including dividends, shareholders have enjoyed a 230% total return.
Related: 7 Best High-Yield Dividend ETFs for Income-Hungry Investors
Best REIT #6: Ventas
- REIT industry: Medical and senior housing
- Market capitalization: $46.1 billion
- Dividend yield: 2.3%
Ventas (VTR) is one of the market’s largest healthcare REITs, boasting about 1,450 properties in the U.S., Canada, and the U.K. This includes more than 850 senior housing communities, with the rest spread across outpatient medical, research, hospitals, long-term acute care, in-patient rehabilitation, and skilled-nursing facilities.
In short: Ventas sits at the intersection of a number of “necessary” healthcare properties.
The broader real estate sector was hobbled during the COVID pandemic, but operators like Ventas were among the hardest hit. VTR in specific hemorrhaged roughly three-quarters of its value in less than two months as residents fled its senior housing and skilled-nursing facilities. That prompted its push into medical office real estate, which provided some stability. But the demographics that lifted senior housing and nursing operators certainly didn’t disappear, and now those properties are back in the spotlight.
Related: 10 Best ‘Rebound’ Stocks to Buy for the Rest of 2026
Ventas isn’t resting on this tailwind, however; it’s also maximizing its senior housing properties by converting many of them from triple-net lease (NNN)—where tenants are responsible for taxes, maintenance, and insurance, and Ventas just cashes a check—to its more actively managed Senior Housing Operating Portfolio (SHOP). These SHOP properties have so far been a significant driver of net operating income (NOI).
“With an ever-aging population and a growing demand for senior living, the company has been returning to its core focus of private-pay senior living communities,” Argus Research analyst Marie Ferguson (Buy) says. “Ventas SHOP assets include independent living, assisted living, and memory care environments, many with high-end amenities which add pricing power. … A solid balance sheet and asset sales will help fund portfolio development. The SHOP segment has momentum and is expected to drive growth in 2026, from NOI [net operating income] growth and from the contributions of $2.5 billion in new investment in 2025.”
“The external growth recovery that we expected for the overall REIT group has been inconsistent, which arguably makes VTR’s external growth dynamic stand out a bit more to us,” add JPMorgan analysts (Overweight, equivalent of Buy), who believe the company has “very good” internal and external growth prospects.
Ventas also was forced to slash its dividend during COVID, from 79¢ per share to 45¢, where it remained for years. However, in Q1 2025, the company finally delivered positive movement, announcing a 6.7% hike to the payout, to 48¢ per share. The company followed that up with an 8.3% boost to 52¢ in Q1 2026.
Related: 13 Best High-Yield Investments [Safe Options Right Now]
Best REIT #5: Ryman Hospitality Properties
- REIT industry: Lodging and hospitality real estate
- Market capitalization: $8.3 billion
- Dividend yield: 3.9%
Ryman Hospitality Properties (RHP) is a specialist within the hotel REIT world. Its properties don’t house bog-standard hotels like Holiday Inn and Motel 6, but instead upscale convention center resorts—and it even owns some entertainment properties, too.
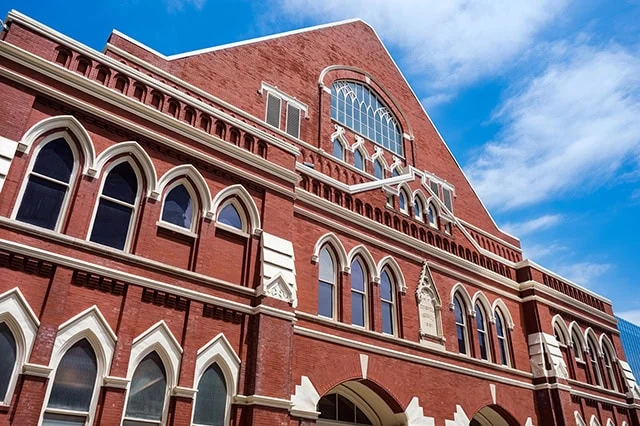
On the property side, its portfolio is composed of just a handful of resorts—but these mega-hotels, including the Gaylord Opryland, JW Marriott San Antonio Hill Country, and Gaylord Rockies, represent almost 14,000 rooms and 3 million square feet of total indoor and outdoor meeting space. In entertainment, the company also owns a roughly 70% controlling ownership interest in Opry Entertainment Group, whose entities include the Grand Ole Opry, Ryman Auditorium, and WSM 650 AM; and a majority interest in festival and events business Southern Entertainment.
“We believe underlying trends remain strong, driven by momentum in forward booking and achieved rates,” says Citi’s Nick Joseph, who rates the stock at Buy. “While positive trends are supportive to near-term performance, we believe investors are likely to be focused on potential sale of the Entertainment division, and possible redeployment of proceeds”
Related: The 10 Best-Rated Dividend Aristocrats Right Now
But Ryman is adding to its portfolio, too. The company in August announced it would buy the 409-acre Grande Lakes Orlando, which includes a 1,010-room JW Marriott and a 582-room Ritz Carlton, which is also managed by Marriott International (MAR).
“RHP’s recent acquisitions include the JW Marriott Hill Country (San Antonio) and the JW Marriott Phoenix Desert Ridge; the acquisition of Grande Lakes is in line with RHP’s recent focus on adding higher-end options to its core-group focus,” Joseph adds. “We view the move as a positive for the portfolio given operational synergies in the Orlando market and potential ADR uplift opportunities.”
As far as the dividend goes: The company had strung together several years’ worth of consecutive dividend increases up until COVID, when the company suspended its 95¢-per-share quarterly payout. That dividend returned in 2022 at a much-reduced 10¢ per share, but quickly ramped up and surpassed its pre-pandemic level. At current levels, the dividend yields almost 4%.
If you prefer to have some exposure to hospitality, the unique nature of both its hotel properties and highly in-demand Nashville entertainment presence make Ryman one of the best REITs to buy.
Related: 8 Best High-Yield Dividend Stocks: The Pros’ Picks
Best REIT #4: American Tower
- REIT industry: Telecommunications
- Market capitalization: $82.0 billion
- Dividend yield: 4.0%
American Tower (AMT) is one of the largest global REITs of any flavor, and its speciality is owning and operating multitenant communications real estate. This includes telecom towers that it rents to wireless providers, fiber optic networks, data centers, and other important infrastructure components that power our digital lives.
With a portfolio of nearly 150,000 different properties and massive demand for telecommunications from both businesses and consumers alike regardless of the macroeconomic picture, AMT offers incredible reliability.
“The company is a leader in tower services, and while domestic mobile spending has flattened, the company is focusing on international expansion of 5G networks and growth in mobile data consumption,” Argus Research’s Ferguson says. “AMT’s strength is in its tower business model. The company owns and leases land and tower access to wireless, radio, and television companies, with multiple tenants per tower. Customers sign long-term leases (with the average lease-term extension around 20 years) and bear the costs of the transmission equipment housed on the company’s towers.”
Truist Managing Director Matthew Niknam (Buy) adds that he likes the company’s “enhanced portfolio mix, with over 70% of property NOI coming from developed markets” and “pristine balance sheet.”
American Tower might raise a few eyeballs from a dividend perspective. That’s because in the first quarter of 2024, it announced a roughly 5% cut in its payout after years of uninterrupted quarterly hikes. However, it still ended up paying out more across 2024 than it did in 2025, and it raised its payout back to $1.70 per share to kick off 2025, then again to $1.79 per share in 2026. So while AMT might not be as frequent a raiser as it once was, the dividend still is growing and continues to look secure.
Make Young and the Invested your preferred news source on Google
Simply go to your preferences page and select the ✓ box for Young and the Invested. Once you’ve made this update, you’ll see Young and the Invested show up more often in Google’s “Top Stories” feed, as well as in a dedicated “From Your Sources” section on Google’s search results page.
Best REIT #3: Essential Properties Realty Trust
- REIT industry: Retail
- Market capitalization: $6.5 billion
- Dividend yield: 4.3%
Essential Properties Realty Trust (EPRT) is a retail REIT, which doesn’t exactly have the best of connotations. More recently, that’s because of the hammering the sector took during COVID, but longer-term, it’s because of the hits that malls and other retail properties have suffered amid the emergence and growth of e-commerce.
Fortunately, EPRT isn’t that kind of retail REIT.
Essential Properties owns and manages more than 2,400 single-tenant properties spanning hundreds of tenants across 48 states. About 77% of the portfolio’s cash annualized base rent (ABR) is service-based, and another 14% or so is experience-focused. In fact, despite being a “retail” REIT, only about 3% of ABR comes from true retail—and the lion’s share of that is from grocery stores, which have been extremely durable. The remaining sliver of ABR comes from industrial properties. Top industries right now include car washes, medical and dental practices, early childhood education, quick-service shops, and automotive service.
So, sure, the word “essential” might be doing a lot of work, but EPRT still isn’t as exposed to economic whims as, say, a mall where most of its stores are selling jeans or jewelry. The diversification helps.
Related: 15 Dividend Kings for Royally Resilient Income
“The top 10 tenants represent <20% of ABR (below peers), the portfolio includes 350+ total tenants, and no tenant is >3% ABR,” says Truist Managing Director Michael Lewis, who counts EPRT among the firm’s highest-conviction Buys. He adds that Essential Properties boasts a “strong balance sheet with sufficient liquidity that can support the growth strategy for the next 12 months.”
But this isn’t just a safety play; Essential Properties can deliver growth, too.
“Essential Properties Realty Trust is one of the fastest-growing net-lease REITs due to its low base and cost of capital spread,” say Stifel analysts, who also call the REIT a Buy. “This has resulted in some of the best earnings growth and among the lowest dividend payout ratios in the space.”
Essential Properties has been more than eager to share the benefits with its stock holders. The company has been raising its dividend semiannually for years; including a modest 3% hike announced in December 2025, the quarterly payout is about 30% higher than where it was five years ago.
Make sure you sign up for The Weekend Tea, Young and the Invested’s free weekly newsletter that over 10k monthly readers use to level up their money know-how.
Best REIT #2: Millrose Properties
- REIT industry: Residential real estate sites
- Market capitalization: $5.1 billion
- Dividend yield: 10.0%
Millrose Properties (MRP) isn’t a run-of-the-mill residential REIT. In fact, it’s a trailblazer.
Millrose was a part of homebuilder Lennar (LEN) until it was spun off in 2024. It buys and develops residential land, then turns around and sells its finished homesites back to Lennar and other homebuilders via options contracts at set fees.
Because of its relative newness and novelty, MRP doesn’t exactly have a crowded coverage base. But the few Wall Street analysts assigned to the company like what they see. That includes Citi’s Nick Joseph, who rates the stock at Buy and is warming on the company’s landbanking partnership with real estate development company JPI.
“We were initially skeptical of MRP’s new multifamily landbanking facility with JPI, as: 1) a large developer would only enter a new facility if it lowered financing costs, enabled new product types, or reduced risk; 2) multifamily construction lending is competitive at lower spreads unless underwriting higher LTVs; and 3) MRP lacks a competitive advantage in underwriting multifamily inputs (e.g. rent levels, cap rates) compared to its real-time for-sale data,” he writes. ” However, in speaking with large apartment developers, institutional capital focused on multifamily landbanking is scarcer than we assumed, and developer equity costs are likely higher than MRP’s option yield—creating an opportunity for MRP to selectively offer permanent financing between traditional debt and equity.”
Perhaps most noteworthy is an extremely aggressive dividend. The company kicked off its program in April 2025 with a prorated 38¢ quarterly distribution, which became 69¢ in July. That dividend has since grown in every quarter since; the most recent 77¢ payout comes out to a 10% yield at current prices.
Related: The 10 Best Dividend ETFs for the Rest of 2026
Best REIT #1: Ellington Financial
- REIT industry: Mortgage
- Market capitalization: $1.7 billion
- Dividend yield: 11.6%
Ellington Financial (EFC) is a mortgage-related real estate investment trust. As previously mentioned, that means elevated risk for several reasons.
First, the fundamentals of trading mortgage paper instead of operating physical properties come with unique risks. Second, a rising-interest-rate environment could pinch EFC as its borrowing costs rise. And lastly, EFC is also the smallest stock on this list—meaning that unlike multibillion-dollar REITs, it simply doesn’t have the same resources to weather any widespread downturns in the economy.
Ellington is a rarity on this list, as it pays a monthly dividend—and a high one at that. And that monthly dividend was actually reduced just a few months after its December 2024 merger with fellow mREIT Arlington Asset Investment Corp., from 15¢ monthly to 13¢, as it worked to absorb Arlington and as a 2022 acquisition, Longbridge Financial, attempted to return to profitability.
Good news on the latter front: Longbridge, a reverse mortgage business, has indeed returned to the black and actually looks attractive as some Baby Boomers choose to remain in their existing homes during retirement.
“We continue to believe a premium to book is warranted given the stable book value, growing mortgage banking businesses (Longbridge and Non-QM [LendSure]), and recent returns that have comfortably covered the dividend,” write Keefe, Bruyette & Woods analysts Bose George and Frankie Labetti (Outperform), who note that home equity conversion mortgage-backed securities (HMBSes) market share reached a new high of 29%, ranking Longbridge the No. 2 issuer.
“On the commercial side, affiliated originator Sheridan Capital continues to grow its footprint, and EFC is institutionalizing the business by building out capital markets and operational infrastructure,” George and Labetti add.
“We continue to see our thesis reinforced by [second-quarter] results,” B. Riley Securities analyst Timothy D’Agostino (Buy) wrote after the company’s most recent earnings report. D’Agostino cites three pillars: “1) EFC’s reverse mortgage originator, Longbridge, as well as EFC’s other differentiated origination platforms; 2) a dynamic platform allowing EFC to shift capital allocation based on the market environment; 3) continued increased long-term financing, [which] should improve the liability side of the balance sheet.”
EFC is well-regarded. Just remember: Mortgage REITs and their lofty yields are on the higher-risk end of the real estate spectrum, and payout cuts are common in this space.
Related: 11 Best Vanguard Funds for the Everyday Investor
REITs: Frequently Asked Questions (FAQs)
Can you buy REITs in funds?
Buying individual REITs like the ones above can be an effective way to tap into the real estate market using publicly traded stocks. But there are also REIT mutual funds and exchange-traded funds (ETFs) out there that provide diversified ways to invest across the sector in one simple holding.
For instance, the Vanguard Real Estate ETF (VNQ) has $38 billion in total assets under management (and that doesn’t include assets under the mutual fund shares). It’s invested in 140 top REITs right now, and it yields a very healthy 3.6%.
REIT ETFs carry their own unique risks, but they can be another effective way to gain exposure to real estate investments in your portfolio and provide consistent retirement income.
How else can you buy real estate?
Typically, if you want to own stock in a real estate company, you have to invest through the public markets. But equity crowdfunding makes it possible for everyday investors to secure a stake in privately held real estate businesses.
Equity crowdfunding platforms typically allow for small investments (read just hundreds or even tens of dollars) in a wide range of businesses. The platform is usually paid through either a monthly fee or by collecting a percentage of the funds raised for the business. And generally speaking, these platforms provide high ease of use compared to many other types of real estate investments.
Equity crowdfunding pick: EquityMultiple
Some real estate crowdfunding platforms only allow you to invest in property portfolios. However, some platforms, such as EquityMultiple, also allow you to invest in individual properties—in this case, commercial real estate (CRE).
EquityMultiple carries a minimum $5,000 initial investment and is limited to accredited investors. However, those investors have access to individual commercial real estate deals, funds, and even diversified short-term notes.
For those interested in learning more about EquityMultiple, consider signing up for an account and going through their qualification process.
- EquityMultiple is a commercial real estate platform for accredited investors, providing investment opportunities in real estate funds, individual properties, and savings alternatives.
- EquityMultiple has a team boasting decades of real estate transaction experience. Their due diligence process whittles down a large selection of properties, accepting only 5% as target investments that they use to build a variety of portfolios that suit numerous investing objectives.
- The company has made $379 million in distributions since its founding.
- Makes commercial real estate Investments accessible
- Intuitive website design
- High net total returns and distributions paid to investors
- Only available to accredited investors
- High investment minimum to begin
- Fee structure varies by investment, complex at times