
If you’re building or adjusting a buy-and-hold retirement portfolio, you certainly don’t need to stay faithful to any single fund provider—different mutual fund companies do some things better than others, after all.
But if you felt compelled to keep your investments within a sole fund family, you could very easily wrap yourself up in some of the best Fidelity retirement funds and meet every one of your needs.
Fidelity has been a leader in mutual funds and exchange-traded funds (ETFs), covering virtually every asset class for decades. It currently boasts nearly 50 million individual investors and nearly $20 trillion in assets under administration—scale that allows it to both add new products over time and keep lowering its already low costs. And the best Fidelity retirement funds can go toe to toe with virtually any other major mutual fund company in terms of price and breadth of offerings.
Better still? While 401(k)s largely let you buy as little or as much of a fund as you want, many mutual fund companies require your initial purchase of a fund to exceed a minimum threshold in the hundreds or thousands of dollars if you’re going through a brokerage, individual retirement account (IRA), health savings account (HSA), and similar plans. But most Fidelity funds have zero minimums. That means you could start buying with as little as $1 depending on your broker’s rules.
Let’s take a look at how Fidelity funds can be used to best position your retirement portfolio. I’ll explore some of the best Fidelity mutual funds for retirement, and provide answers to some common related retirement investing questions.
Editor’s Note: The tabular data presented in this article is up-to-date as of Sept. 15, 2026.
Disclaimer: This article does not constitute individualized investment advice. Individual securities, funds, and/or other investments appear for your consideration and not as personalized investment recommendations. Act at your own discretion.
What Should You Look for When Evaluating a Retirement Fund?
Here are some of the most critical factors to consider when you start investing your retirement savings in tax-advantaged retirement accounts such as 401(k)s and IRAs:
- Costs: When you buy an investment fund, you pay an “expense ratio.” For instance, if a fund charges a 0.5% expense ratio, that means for every $1,000 you have invested in that fund, you’re spending $5 paying the fund company. “It’s only five bucks.” Sure. But it’s five bucks that can no longer grow and compound for you over time. The general idea, then, is if all else is equal, the lower the cost, the better. Some funds can justify their fees with historically superior performance, but Fidelity has nothing to apologize for—the best Fidelity retirement funds charge fees that typically sit near or at the bottom of their category.
- Income: You ideally want your retirement portfolio to produce at least some regular income—in the form of both bond interest and dividend income. Stock prices can suffer during nasty corrections and bear markets, but income-generating funds can help provide for your living expenses without forcing you to sell at an inopportune time. How much income your account should produce depends on your own circumstances. For instance, older investors tend to be more concerned with income while younger investors focus more on growth.
- Taxes: A taxable account (like a standard brokerage account) is better suited to take advantage of certain tax-advantaged investments, such as municipal bonds. For tax-advantaged accounts, such as HSAs, some of the best investments include bond funds (where the interest income won’t be taxed) and actively managed stock funds (where the capital gains distributions from heavy trading, aka “turnover,” won’t be taxed).
- Diversification: You’ve likely always been told that you should hold a diversified portfolio, which means that you hold a variety of investments, not just one or two. That could mean holding multiple assets (stocks, bonds, commodities), but that could also mean holding, say, stocks from different countries, or stocks from different sectors. And investment funds, which can own any number of stocks, bonds, or other holdings all at once, can help you achieve that diversification. But every fund has its own level of built-in diversification. Some funds hold dozens of stocks while others hold thousands. Some funds invest heavily in their biggest stocks while others spread their assets out more evenly. So always consider how diversified a fund really is, as well as whether that level of diversification suits your needs.
Why Fidelity Mutual Funds?
Fidelity is a leader in mutual funds (and exchange-traded funds [ETFs], for that matter) and has been a force in the industry since the launch of its Fidelity Puritan Fund (FPURX) back in 1947.
Today, this premier mutual fund company has $18 trillion in assets under administration thanks in large part to the success of its talented fund managers. Most notably, that includes Peter Lynch, the longtime manager of the Fidelity Magellan Fund (FMAGX) who averaged an incredible 29.2% per year between 1977 and 1990. But Fidelity can also thank other successful managers, such as Joel Tillinghast and Will Danoff.
However, while Fidelity first built its name on actively managed funds, over the past three decades, the firm has built out its low-cost and even no-cost index funds as part of the movement to reduce expense ratios and transaction costs for individual investors.
Empower Advisory Group offers a comprehensive wealth management service known as Personal Strategy Investment Services.
This managed account solution provides clients with discretionary investment management, personalized portfolio construction, and access to financial planning support.
The Best Fidelity Retirement Funds to Buy
With the introduction behind us, let’s choose some of the very best Fidelity retirement funds to round out a portfolio.
Any or all of these mutual funds are ideal holdings for a tax-deferred retirement plan like an IRA or 401(k) plan given their tax consequences, but some are perfectly at home in a good old-fashioned brokerage account.
Best Fidelity Retirement Fund #1: Fidelity 500 Index Fund
- Style: U.S. large-cap stock
- Management: Index
- Assets under management: $859.2 billion
- Dividend yield: 1.0%
- Expense ratio: 0.015%, or 15¢ per year for every $1,000 invested
- Minimum initial investment: None
I’ll start with the type of fund I virtually always look at when compiling “best-of” fund lists: an S&P 500 index fund.
Why? Well, the S&P 500 Index is made up of hundreds of America’s biggest and most recognized companies, it’s one of the most renowned stock-market indexes in the world, and most importantly, it’s one of the most productive indexes, too. Even professional money managers struggle to beat it; according to the most recent S&P Dow Jones Indices data, just 14% of actively managed large-cap mutual funds have outperformed the S&P 500 over the trailing 10-year period, and that number shrinks to a mere 10% when looking at the past 15 years.
“I know guys that rate active managers in all these categories, and even they’re like, ‘I’m not buying actively managed large blend; I’m just indexing,'” says Daniel Sotiroff, Senior Analyst for ETF and Passive Strategies at Morningstar. “Because it’s so brutally tough to beat a dirt-cheap index fund in the large blend category.”
Even Warren Buffett, the Oracle of Omaha himself—considered by many to be the greatest investor in history—has said on multiple occasions that most investors, most of the time, should simply buy and hold an S&P 500 index fund and let it run.
Related: The 11 Best Fidelity Funds to Buy Now
That’s why owning a fund like the Fidelity 500 Index Fund (FXAIX) is one of the smartest moves you can make for your long-term retirement portfolio.
FXAIX in particular is one of the most cost-effective ways to buy the S&P 500. The Fidelity 500 Index Fund has an almost nonexistent expense ratio of just 0.015%, which is just about impossible to beat. That undercuts not just virtually all of its mutual fund peers, but S&P 500 ETFs, too. This extremely low fee has helped FXAIX draw an incredible $825 billion or so in assets under management, and it’s why I rank FXAIX among the best mutual funds you can buy.
As I mentioned above, when evaluating a retirement fund, you’ll always want to consider “turnover” (the percentage of a fund’s holdings that are cycled out of the fund in a given year). High turnover means a lot of trading costs, which are passed on to investors in the form of capital gains distributions, which are taxable … but you can avoid that tax hit by holding high-turnover funds in tax-advantaged retirement accounts like 401(k)s and IRAs.
Fidelity 500 and other S&P 500 index funds tend to have extremely low turnover, at just a couple percent annually, meaning it pays little to no capital gains distributions. Thus, Fidelity 500 will do just fine in a regular ol’ taxable brokerage account. However, given that many people only invest through tax-advantaged retirement accounts, and given that S&P 500 funds will typically make up the core of your portfolio no matter your account type, FXAIX remains a great holding for any retirement account.
Want to learn more about FXAIX? Check out the Fidelity provider site.
Related: The 10 Best Fidelity ETFs You Can Buy [Invest Tactically]
Best Fidelity Retirement Fund #2: Fidelity Zero Total Market Index Fund
- Style: U.S. large-cap stock
- Management: Index
- Assets under management: $41.0 billion
- Dividend yield: 0.9%
- Expense ratio: N/A
- Minimum initial investment: None
Until a mutual fund company starts paying you to own its products, Fidelity’s ZERO line of mutual funds is as cheap as you’re going to get.
That’s because they charge nothing. Their annual expense ratio is a big, fat donut.
Fidelity Zero Total Market Index Fund (FZROX) is a different strategy than the S&P 500, of course. FXAIX is a “large-cap” fund, while FZROX—which tracks the Fidelity U.S. Total Investable Market Index—is a “total market” fund. That means it holds stocks of all sizes. However, in practice, the funds aren’t terribly dissimilar. FXAIX holds an 80/19/1 blend of large-, mid-, and small-cap stocks, while FZROX’s portfolio is a 72/20/8 blend.
For whatever it’s worth, you’re technically not investing in the entire stock market. To keep costs down, Fidelity Zero Total Market Index uses statistical sampling techniques to replicate the returns of the index without having to own every underlying stock. Still, FZROX currently holds 2,608 stocks. From a practical perspective, that’s as close to the whole stock market as anyone would need to get.
How much do those costs matter? Honestly, there’s little difference between an expense ratio of 0.015% and zero. That extra 15¢ per year per $1,000 invested isn’t going to make a material difference over an investing lifespan. But it’s also not nothing. So if paying the absolute minimum in fees is philosophically important to you, these ZERO products—which cover a few core portfolio needs—could absolutely be treated as Fidelity retirement funds.
However, to invest in FZROX, or any other Fidelity ZERO fund, you must have a Fidelity brokerage account. If you don’t have a Fidelity brokerage account but want comparable exposure, the Fidelity Total Market Index Fund (FSKAX) charges a barely noticeable 0.015% in annual expenses and has the same zero minimum initial investment.
Want to learn more about FZROX? Check out the Fidelity provider site.
Related: 11 Best Vanguard Funds for the Everyday Investor
Best Fidelity Retirement Fund #3: Fidelity Select Pharmaceuticals Portfolio (NEW)
- Style: Industry (Pharmaceuticals)
- Management: Active
- Assets under management: $1.6 billion
- Dividend yield: 2.5%
- Expense ratio: 0.67%, or $6.70 per year for every $1,000 invested
- Minimum initial investment: None
The Fidelity Select Pharmaceuticals Portfolio (FPHAX), the latest addition to our list, is a play on the part of the healthcare sector that creates life-improving (and sometimes life-saving) treatments.
While healthcare is one of the most well-rounded sectors, the defensive and income elements tend to come from the pharmaceutical industry’s big, cash-rich drug companies that historically pay bigger dividends than “growthier” health industries.
Of course, technically, manager Karim Suwwan de Felipe doesn’t just focus on pharmaceuticals. Pharma makes up the lion’s share of assets at around 80%, but there’s a sizable remainder, which is virtually entirely invested in biotechnology companies. (The difference is in the types of treatments—pharmaceuticals use chemical compounds while biotechs are based on living organisms. But otherwise, they’re extremely similar businesses and belong under the same umbrella.)
FPHAX currently owns about 60 companies. Large caps command the majority of assets (65%), but the fund invests a healthy 15% or so in small companies, with the remaining 20% going to mid-caps. It’s not exactly a balanced portfolio from an individual-holding standpoint, either; weight-loss drug giant Eli Lilly (LLY) accounts for more than a quarter of assets all by its lonesome, and the U.K.’s GSK (GSK) is just under 10% of assets.
But big bets have often paid off for Suwwan de Felipe, whose fund performance ranks within the top 10% of the category competition across the trailing five- and 10-year time frames, and among the top quarter over the past three and 15 years. Meanwhile, the presence of several blue-chip pharma names helps throw off a solid yield well north of 2%.
Want to learn more about FPHAX? Check out the Fidelity provider site.
Make sure you sign up for The Weekend Tea, Young and the Invested’s free weekly newsletter that over 10k monthly readers use to level up their money know-how.
Best Fidelity Retirement Fund #4: Fidelity Trend Fund
- Style: U.S. large-cap growth stock
- Management: Active
- Assets under management: $4.6 billion
- Dividend yield: < 0.1%
- Expense ratio: 0.74%, or $7.40 per year for every $1,000 invested
- Minimum initial investment: None
An old Wall Street maxim says “you never go broke taking a profit.” There is a lot of wisdom in that quote. As a general rule, buying and holding good stocks or good funds and allowing them to compound over years or even decades is the way to go. But having at least part of your portfolio in actively traded strategies can also make sense, particularly in bear markets. Actively traded strategies have their stretches when they outperform passive index strategies, and they can potentially help you to avoid major declines.
Unfortunately, active trading strategies are also woefully tax-inefficient, particularly if your holding period is less than a year. Short-term capital gains are taxed as ordinary income, meaning you could be sharing up to 37% of your gains with Uncle Sam.
Related: The 16 Best ETFs to Buy for the Rest of 2026
So, it makes sense to hold funds that do a lot of active trading in a tax-deferred retirement account. There is no precise, universally accepted threshold for what constitutes “a lot” of active trading, but I would consider any fund with portfolio turnover (how much of the portfolio’s holdings are turned over, or replaced, in a given year) over 30% or so to be fairly tax-inefficient. The higher that number goes, the more inefficient the fund.
As an example, let’s look at the Fidelity Trend Fund (FTRNX). This is a fairly aggressive fund that focuses on companies the manager believes have above-average growth potential. Unsurprisingly, FTRNX is extremely heavy in tech names such as Nvidia (NVDA) and Apple (AAPL); the sector accounts for 45% of assets right now.
The fund has historically done well: It has has beaten its Morningstar category average over every meaningful time period, and it’s in the top 20% (or better) of its peers by performance across those time frames, too. But this high performance comes at the cost of a lot of active trading; the annual portfolio turnover is 60%. In a taxable account, the resulting capital-gains distributions represent a large potential tax liability. Thus, FTRNX is exactly the kind of actively managed fund best held in a tax-advantaged retirement account.
Want to learn more about FTRNX? Check out the Fidelity provider site.
Related: 8 Low- and Minimum-Volatility ETFs for Peace of Mind
Best Fidelity Retirement Fund #5: Fidelity Nasdaq Composite Index Fund

- Style: U.S. large-cap growth stock
- Management: Index
- Assets under management: $28.0 billion
- Dividend yield: 0.5%
- Expense ratio: 0.29%, or $2.90 per year for every $1,000 invested
- Minimum initial investment: None
When you visit a financial website or look at a business channel chyron, you’ll typically see data for the S&P 500 and Dow Jones Industrial Average prominently displayed. That’s because when the average person asks “how did the stock market do today?” they’re typically asking about one of these two American stock-market benchmarks.
They’re probably not asking about the Nasdaq Composite Index.
The market cap-weighted Nasdaq Composite Index is made up of all the roughly 3,300 stocks that are listed on the Nasdaq Composite, which serves alongside the New York Stock Exchange as the world’s two largest stock exchanges by market capitalization. And while it holds a place of prominence right alongside the S&P 500 and DJIA, it’s less as a broad-market index, and more as a proxy of the tech sector.
That makes the Fidelity Nasdaq Composite Index Fund (FNCMX) particularly interesting as a Fidelity retirement fund for anyone who wants to be more aggressive with the equity portion of their portfolio.
FNCMX holds around 2,700 Nasdaq Composite stocks—not the index’s full roster, but a representative amount accounting for the vast majority of the index’s market cap. Large-cap growth funds normally favor tech and tech-esque companies, but Fidelity Nasdaq Composite Index is even more concentrated in those holdings than competitor funds. As I write this, more than half of the fund’s assets are invested in the technology sector, and another 30% are split between the communications services sector and the consumer discretionary sector, which includes technology-adjacent mega-caps like Amazon (AMZN) and Tesla (TSLA).
That said, while FNCMX is an aggressive product, it’s not a trading hive. Turnover is actually minimal, at just 4%. That makes this Fidelity fund fairly tax-efficient, and thus perfectly appropriate for taxable accounts and tax-advantaged accounts alike.
Want to learn more about FNCMX? Check out the Fidelity provider site.
Related: 13 Best Stock & Investment Newsletters for Inbox Alpha
Best Fidelity Retirement Fund #6: Fidelity Worldwide Fund
- Style: Global large-cap growth
- Management: Active
- Assets under management: $3.9 billion
- Dividend yield: 0.5%
- Expense ratio: 0.77%, or $7.70 per year for every $1,000 invested
- Minimum initial investment: None
The United States is the world’s leading innovation hub as well as its largest economy. And if you are an American and your expenses are in dollars, it only makes sense to keep the bulk of your wealth in U.S. stock and bond funds.
Still, there are thousands of quality companies in developed markets like Europe, Canada, Australia, or wealthier Asian markets like Japan or South Korea, and in emerging markets (less stable but faster-growing) like China and India. And while U.S. stocks have led the world over the past decade, there are long stretches when international stocks outperform, such as 2000-08, and in 2025.
If you want exposure to international stocks, you generally have two broad options: 1.) Buy an “international” stock fund, which will hold companies headquartered outside of the U.S. 2.) Buy a “global” stock fund, which will hold both domestic and international companies.
Related: 12 Best Vanguard ETFs You Can Buy [Build a Low-Cost Portfolio]
Fidelity Worldwide Fund (FWWFX), for instance, provides a blend of exposure typical to many global funds: Two-thirds of assets are invested in U.S. equities, while the remainder is allocated to foreign stocks. Most of that international presence comes from developed-market countries such as the U.K., Canada, and Japan, but FWWFX does provide a little exposure to emerging markets, including Taiwan and China.
Co-Managers Andrew Sergeant and Stephen DuFour have “a holistic and long-term view,” prioritizing “above-average growth prospects … stable and high returns on capital, durable competitive positions, consistent profitability,” and other qualities.
Their strategy has been plenty successful. FWWFX has a stellar long-term record—it has beaten its Morningstar category and index over the trailing three-, five-, 10-, and 15-year periods, and it’s among the top 20% of category funds by performance over every meaningful time frame.
Despite their long view, Sergeant and DuFour do quite a bit of trading. Annual turnover is 144%, which effectively means that within a year, the entire portfolio has flipped … and another 44% of those new positions have flipped, too! That means capital gains distributions are a given; historically, some of those capital gains have been short-term in nature and thus taxed at less favorable ordinary income rates.
That’s a problem you can easily snuff out by holding Fidelity Worldwide in tax-advantaged retirement accounts.
Want to learn more about FWWFX? Check out the Fidelity provider site.
Best Fidelity Retirement Fund #7: Fidelity Investment Grade Bond Fund
- Style: U.S. intermediate-term core bond
- Management: Active
- Assets under management: $11.8 billion
- SEC yield: 4.7%*
- Expense ratio: 0.45%, or $4.50 per year for every $1,000 invested
- Minimum initial investment: None
Most investors need some exposure to bonds, which is debt that’s issued by governments, companies, and other entities. Their interest payments and relative lack of volatility make them an excellent tool for providing a portfolio with stability and income.
Individual bonds can be a hassle, however. Data and research on individual issues is much thinner than it is for publicly traded stocks. And some bonds have minimum investments in the tens of thousands of dollars. But you can blunt these problems by purchasing a bond fund, which allows you to invest in hundreds or even thousands of bonds with a single click—and, in many cases, very low fees.
That makes core bond funds such as the Fidelity Investment Grade Bond Fund (FBNDX) attractive buy-and-hold products for retirement planners who, when it comes to their debt exposure, want to hand the reins over to skilled managers. And now that the yield curve has normalized, investors looking for fixed income are once again being rewarded for buying bonds a little longer in maturity.
FBNDX’s five co-managers have built a portfolio of about 4,900 investment-grade securities spanning numerous debt types, including U.S. Treasuries, corporate bonds, pass-through mortgage-backed securities (MBSes), commercial MBSes, asset-backed securities (ABSes), and other debt. The portfolio’s bond maturities range between just a few months and 20 years, though the biggest allocation (about half of assets) is to intermediate-term bonds of five to 10 years until maturity.
Duration—a measure of interest-rate sensitivity—is 6.0 years. In theory, this means if interest rates were to rise by 1 percentage point, the portfolio should experience a short-term capital loss of about 6.0%. Likewise, a 1-percentage-point decline in interest rates would result in a 6.0% increase in short-term capital gains.
Long story short: Fund shareholders are instantly plugged into a widely diversified and well-selected set of fixed-income assets, which generate a decent stream of income, and at a very reasonable cost. This makes FBNDX one of the best Fidelity retirement funds to buy.
* SEC yield reflects the interest earned across the most recent 30-day period. This is a standard measure for funds holding bonds and preferred stocks.
Want to learn more about FBNDX? Check out the Fidelity provider site.
Related: 10 Monthly Dividend Stocks for Frequent, Regular Income
Best Fidelity Retirement Fund #8: Fidelity Short-Term Treasury Bond Index Fund
- Style: U.S. short-term government bond
- Management: Active
- Assets under management: $3.6 billion
- SEC yield: 4.3%
- Expense ratio: 0.03%, or 30¢ per year for every $1,000 invested
- Minimum initial investment: None
Short-term bonds are a great source of safety. However, how much yield they’ll give you depends on the interest-rate environment. For instance, bonds with short maturities currently offer relatively high income for relatively low risk. And that makes products such as Fidelity Short-Term Treasury Bond Index Fund (FUMBX) particularly attractive.
FUMBX is a suitable product for investors who want to earn some money on their investment but don’t want to take on a lot of risk. Why? Well, it comes down to two principles:
- In general, the higher an issuer’s credit quality, the higher the implied likelihood that an investor will get their full interest and principal. Not much beats U.S. Treasuries, which are among the best-rated bonds on the planet. (That said, it’s often true that the higher the bond’s quality, the less yield an issuer must offer to draw interest in that bond.)
- Bonds with shorter maturities reduce risk, too. Let’s say you’re choosing between two bonds from the same issuer: Bond A, which matures in two years, and Bond B, which matures in 20 years. Everything else being equal, you’d probably feel safer with Bond A, given that a lot could happen in the additional 18 years Bond B needs to mature! That’s also why short-term bonds have less interest-rate risk. When rates go higher, new bonds pay more, which tempt people to sell their old bonds for the new, higher-paying bonds. However, the temptation is much greater when you’re dealing with longer-term bonds with lots of payments remaining—and not so great for short-term bonds with one or just a couple payments left.
FUMBX combines these two ideas.
This Fidelity fund holds a tight grouping of about 115 Treasury bond issues whose maturities span a few months to five years. That’s a bit longer-term than some other Treasury funds that limit their maturities to three years. But it still results in a portfolio average maturity of under three years, which is plenty short. Duration, meanwhile, is a scant 2.5 years, which suggests FUMBX would suffer a modest 2.5% short-term decline in response to a 1-percentage-point hike in interest rates. Conversely, it would only rise that much on a similar decline in rates.
Meanwhile, this relatively safe portfolio still throws off more than 4% in yield, and that income is exempt from state and local taxes. So if you want portfolio protection that can still generate some income, Fidelity Short-Term Treasury Bond Index Fund is one of the best Fidelity retirement funds to buy.
Want to learn more about FUMBX? Check out the Fidelity provider site.
Related: 8 Best T. Rowe Price Funds to Buy for the Rest of 2026
Best Fidelity Retirement Fund #9: Fidelity Government Money Market Fund
- Style: Money market
- Management: Active
- Assets under management: $461.3 billion
- SEC yield: 3.3%
- Expense ratio: 0.42%, or $4.20 per year for every $1,000 invested
- Minimum initial investment: None
It didn’t seem like it would be the case at the start of 2026, but as I write this, stock-market futures imply that there’s a better chance that rates will go up from here rather than down. If that happens, longer-dated bonds would likely experience capital losses. That was certainly the case in 2022, when very long-term bonds actually saw greater declines than common stock indexes like the S&P 500.
If you are looking for a competitive yield with essentially no interest-rate risk at all, the Fidelity Government Money Market Fund (SPAXX) is a solid option and one of the very best Fidelity retirement funds for your HSA. This income fund consists entirely of U.S. Treasury bills and other U.S. government obligations and repurchase agreements.
Right now, for instance, more than 40% of assets are invested in repurchase agreements backed by Treasury securities. Another 20% is tied up in Treasury bills, 20% is invested in agency floating-rate securities, and the remainder is tied up in fixed-rate agency securities (e.g., Fannie Mae and Freddie Mac securities) and Treasury coupons.
Money market funds are somewhat unique among mutual funds in that they specifically target a net asset value of $1 per share. Any earnings that cause the net asset value to go higher than $1 get distributed as dividends. This means that, unless you reinvest your dividends, the value of your money market mutual fund will not grow over time. This makes SPAXX an extremely conservative option with extremely limited possibility of loss. In fact, while SPAXX doesn’t have a listed Morningstar Portfolio Risk Score, it’s nonetheless one of the most conservative Fidelity funds you can own.
That said, money market funds’ yields are very sensitive to Federal Reserve policy moves. As recently as 2022, money market funds in general offered virtually nothing in yield. The Fed’s most aggressive string of rate hikes in history changed that—so much so that even after rate cuts in 2024 and 2025, SPAXX remains a legitimate income fund with a yield well north of 3%. Still, if you require a certain level of income, closely watch both the Fed and the fund, and be aware of other options should the central bank’s easing continue.
Until then, low risk and a competitive yield make SPAXX one of the very best Fidelity retirement funds period, though it’s best off in an HSA or other tax-advantaged account. That’s because money market funds are effectively bond funds, with interest income the predominant source of returns. Interest income is taxed as ordinary income—if you’re in the 37% federal tax bracket, then you’re losing 37% of your bond interest to taxes—making bond funds (and money market funds) extremely tax-inefficient.
* SEC yield for money market funds reflects the interest earned across the most recent 7-day period.
Want to learn more about SPAXX? Check out the Fidelity provider site.
Related: 8 Best Acorns Alternatives [Better Micro-Investing Apps]
Best Fidelity Retirement Fund #10: Fidelity Freedom Funds
- Style: Target-date
- Management: Active or index, depending on Freedom series
- Expense ratio: Fidelity Freedom Funds: 0.46%-0.68%, or $4.60-$6.80 per year for every $1,000 invested; Fidelity Freedom Index Funds: 0.12%, or $1.20 per year for every $1,000 invested; Fidelity Freedom Blend Funds: 0.41%-0.47%, or $4.10-$4.70 per year for every $1,000 invested; Fidelity Freedom Sustainable Target Date Funds: 0.41%-0.49%, or $4.10-$4.90 per year for every $1,000 invested
- Minimum initial investment: None
One of the issues in building an appropriate retirement allocation is that your ideal mix of stock and bond funds will evolve over time based on your age and stage of life. An ideal portfolio for a 20-year-old is likely going to be very different from that of a 40-year-old, and both those portfolios will be different from what’s ideal for a 60-year-old.
This is where a target date fund can really be a lifesaver. A target-date fund—also called a life-cycle fund—is a type of mutual fund that is designed to change its asset allocation over time.
The typical target-date fund is an actively managed fund—one that will start out with a heavy allocation to stocks and then slowly transition to a heavier allocation to bonds as it approaches its target retirement date, following a glide path.
The target retirement date is intended to be a rough estimate and doesn’t need to be precise. You’re generally not going to know the precise year you plan to retire decades in advance. Fidelity, like most mutual fund families, creates its target-date funds in five-year increments of target retirement date (say, 2025, 2030, 2035, etc.).
Fidelity mutual funds have excellent reputations for their low costs and breadth of offerings, and Fidelity’s target-date fund families continue that legacy. They include the Fidelity Freedom Funds, as well as a sustainable target-date lineup:
- Fidelity Freedom
- Fidelity Freedom Index
- Fidelity Freedom Blend
- Fidelity Target Date Sustainable
These Fidelity target-date funds hold portfolios of mostly Fidelity stock and bond mutual funds, they’re cheap, and they have no required minimum investment. They’re among the best suites of life-cycle funds you can buy, and you can read more about them in our primer on Fidelity target-date funds.
Want to learn more about Fidelity Freedom Funds? Check out the Fidelity provider site.
Related: The 10 Best Dividend ETFs [Get Income + Diversify]
Learn More About These and Other Funds With Morningstar Investor
If you’re buying a fund you plan on holding for years (if not forever), you want to know you’re making the right selection. And Morningstar Investor can help you do that.
Morningstar Investor provides a wealth of information and comparable data points about mutual funds and ETFs—fees, risk, portfolio composition, performance, distributions, and more. Morningstar experts also provide detailed explanations and analysis of many of the funds the site covers.
With Morningstar Investor, you’ll enjoy a wealth of features, including Morningstar Portfolio X-Ray®, stock and fund watchlists, news and commentary, screeners, and more. And you can try it before you buy it. Right now, Morningstar Investor is offering a free seven-day trial and a discount on your first year’s subscription when you use our exclusive link.
- Morningstar Investor offers expert research, investing analysis, and advisor-grade portfolio management tools that are tailor-made for buy-and-hold investors.
- Morningstar is one of the most prized sources of mutual fund and exchange-traded fund (ETF) data in the world.
- How does your portfolio stack up? Put it through Morningstar's Portfolio X-Ray, which will provide insights such as whether you have too many overlapping holdings or whether you're paying too much in fees.
- Special Offer 1: Click our sign-up link to receive $50 off your first year of Morningstar Investor. (Annual plan only.)
- Special Offer 2: Students receive one year of Morningstar Investor access for just $25!
- Special Offer 3: Teachers receive a 60% discount on Morningstar Investor access.
- Top-flight fund research and analysis
- Portfolio management tool
- Powerful screener
- Watchlists
- Tailored news and commentary
- Below-average charting
- High monthly billing rate
Related: 10 Best Low-Cost Fidelity Index Funds to Buy Now
Track Your Portfolio With Empower
- Available: Sign up here
- Price: Tools: Free. Wealth Management: Starts at 0.89% of assets annually.*
Empower is one of our top-rated financial services firms for people of any income level thanks to the quality and breadth of its offerings:
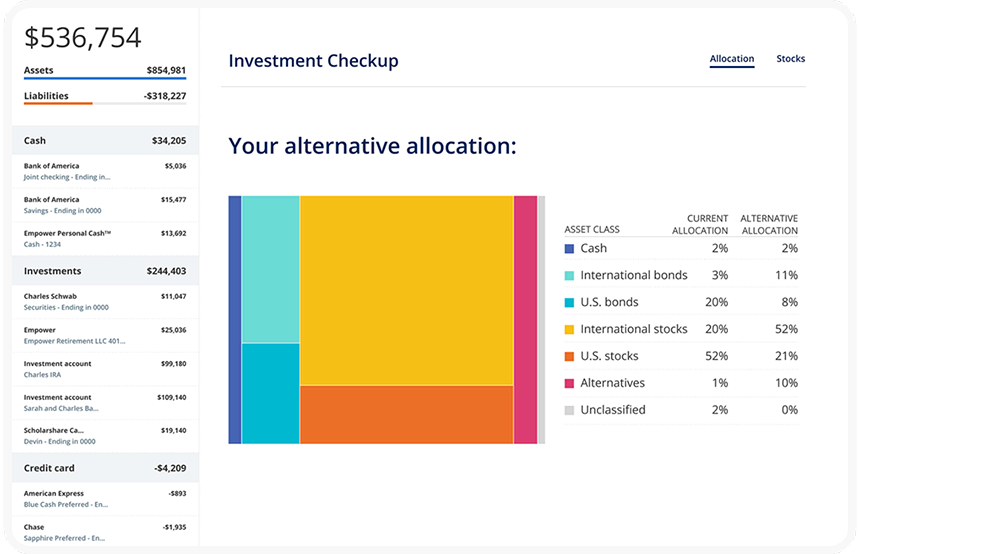
- Free financial tools: Empower’s free Personal Dashboard includes a host of useful tools, including a savings planner, retirement planner, financial calculators, and even a cost planner for your children’s education. But the tool that sets Empower apart is its Investment Checkup tool, which assesses portfolio risk, analyzes past performance, provides a target allocation for your portfolio, and lets you compare your portfolio to the S&P 500 and Empower’s “Smart Weighting” Recommendation.
- Fee-based wealth management services: Empower also offers several suites of advisory services depending on your investible assets. People with as little as $100,000 can get unlimited financial advice and retirement planning and a professionally managed portfolio. Clients with higher assets can access more services, including dedicated financial advisors, specialists in areas such as real estate and stock options, and even access to private equity.
Use our exclusive link to sign up for the Empower Personal Dashboard, whether that’s for the free tools or the advisory services. If you have $100,000 or more in investible assets, you’ll also be able to schedule a free initial 30-minute financial consultation with an Empower professional.
- Empower offers both a free set of portfolio, net worth, and cash flow tracking tools, as well as paid asset management service.
- Link Empower to your bank and investing accounts, credit cards, and more to see a single view of useful information and data, including your net worth.
- Empower Advisory Group offers a comprehensive wealth management service known as Personal Strategy. This managed account solution provides clients with discretionary investment management, personalized portfolio construction, and access to financial planning support. Accounts investing $100k to $250k receive unlimited advice and retirement planning help from financial advisors, as well as a professionally managed ETF portfolio with reviews upon request. Higher asset tiers offer access to dedicated advisors, estate planning, and tax specialists, plus additional investment options like access to private equity.**
- Special offer: If you have $100k+ in investible assets, sign up with our link to schedule a free initial 30-minute financial consultation with an Empower professional.
- Free portfolio tracker (Dashboard)
- Free net worth, cash flow, and investment reporting tools (Dashboard)
- Tax-loss harvesting (Personal Strategy)
- Dividend reinvestment (Personal Strategy)
- Automatic rebalancing (Personal Strategy)
- Low investment expense ratios (Personal Strategy)
- High number of investment accounts supported (Personal Strategy)
- Low $100k minimum for investment management (Personal Strategy) compared to traditional advisors.
- Moderately high investment management fee (0.89% AUM) compared to other online advisors (Personal Strategy)
- No dedicated advisor unless you have $250k+ in assets
Fidelity Funds for Retirement: Frequently Asked Questions (FAQs)
What are Fidelity ZERO Funds?
Fidelity ZERO Funds are a line of zero-minimum, zero-expense index funds launched by Fidelity in 2018. Currently, there are four Fidelity ZERO funds:
- Fidelity Zero International Index Fund (FZILX)
- Fidelity Zero Total Market Index Fund (FZROX)
- Fidelity Zero Extended Market Index (FZIPX)
- Fidelity Zero Large Cap Index Fund (FNILX)
The ZERO funds are true to their name: Investors literally pay nothing in management fees. But there are conditions. The Fidelity ZERO funds are only available in Fidelity brokerage accounts. That might not be a problem, as Fidelity brokerage accounts are generally well regarded and competitive with the other major online brokers. But if you do not already have a Fidelity account, you’d need to open one.
Fidelity ZERO Funds are, strictly speaking, index funds. But they are based on customized indexes that Fidelity has created in-house. The typical large-cap index fund tracks the S&P 500 or another recognized index, but they have to pay licensing fees to the index creator. Fidelity avoids the licensing fees by creating their own indexes, which allows them to pay the savings on in the form of zero fees.
The Fidelity indexes tend to be very similar to popular indexes such as the S&P 500, but they are not the same. So, if tracking a specific index is a priority for you, you should take that under advisement.
What is the minimum investment amount on a Fidelity fund?
Every Fidelity fund has its own minimum investment amount specific to that fund. But Fidelity has been a trailblazer in making its funds available to beginning investors with ultra-low minimums, and many Fidelity funds have no minimum investment at all.
Part of our criteria in selecting the best Fidelity index funds was accessibility, and every fund selected here has a minimum investment of zero, meaning you can literally start your investment with any dollar amount.
Want to talk more about your financial goals or concerns? Our services include comprehensive financial planning, investment management, estate planning, taxes, and more! Schedule a call with Riley to discuss what you need, and what we can do for you.